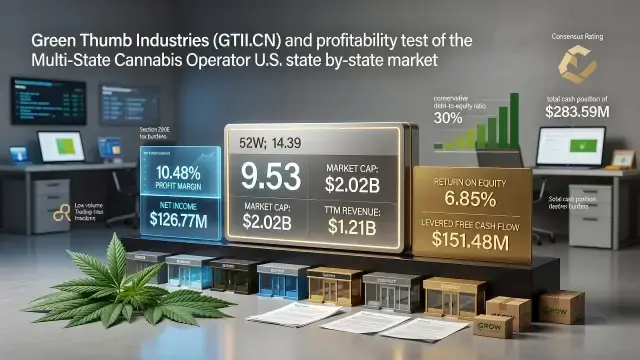
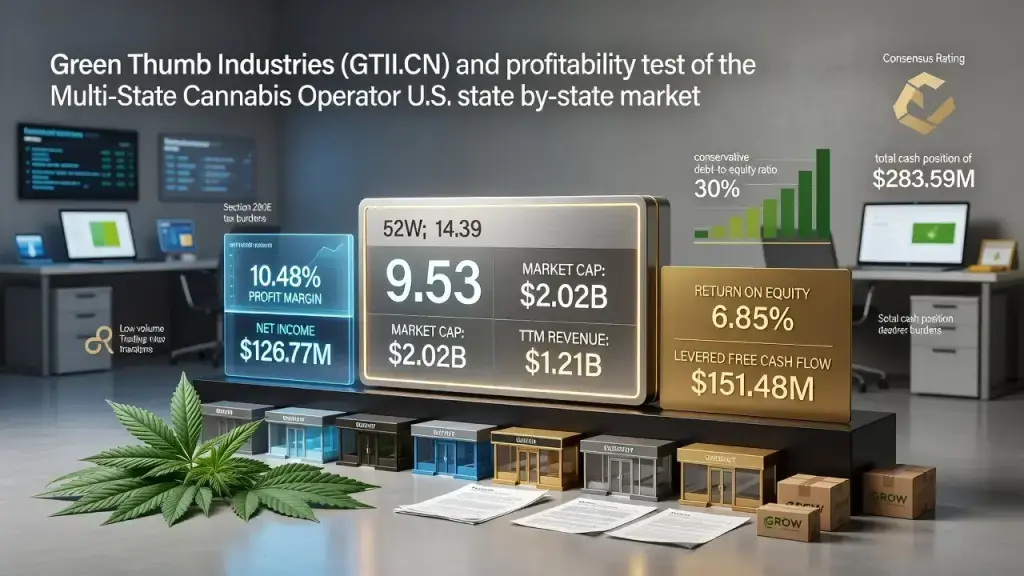
Green Thumb Industries (GTII.CN) closed its most recent session at 9.53, well off its 52-week high of 14.39, a gap that tells a story bigger than one stock ticker. The multi-state operator carries a market capitalization near 2.02 billion dollars and trailing twelve-month revenue of 1.21 billion, numbers that place it among the larger vertically integrated cannabis companies trading on Canadian exchanges while its core operations remain tied to U.S. state-by-state licensing regimes.
What the Numbers Say About Operating Discipline
A profit margin of 10.48 percent and net income of 126.77 million dollars on that revenue base is, frankly, not a small feat in this sector. Federal cannabis prohibition still forces multi-state operators to absorb the burden of Section 280E, the tax code provision that bars cannabis businesses from deducting ordinary business expenses the way a grocery chain or pharmacy would. That single rule quietly eats into margins across the industry, and it's part of why analysts watch return on equity - here, 6.85 percent - as closely as they watch top-line growth. Green Thumb's levered free cash flow of 151.48 million dollars suggests the company is generating real cash after capital spending, not just reporting paper profit, which matters a great deal to operators trying to fund expansion without diluting shareholders.
Why the Stock Trades Below Its Own 52-Week High
The 52-week range - from essentially zero trading activity days to a peak of 14.39 - reflects how thinly some cannabis equities trade on the Canadian Securities Exchange, where many U.S. plant-touching companies list because major American exchanges still restrict cannabis issuers tied to federally illegal activity. Low average volume, in this case around 154,272 shares, can exaggerate price swings on days when institutional buyers or sellers step in. That's not unique to Green Thumb; it's a structural feature of the sector. Until federal rescheduling or banking reform changes the equation, cannabis stocks will keep behaving more like regulated utilities with regulatory overhang than conventional consumer retailers.
What This Means for Operators and Wholesale Partners
For dispensary operators and wholesale brands that supply or compete with Green Thumb's retail footprint, the company's financial posture offers a useful benchmark. A debt-to-equity ratio of roughly 30 percent signals a relatively conservative balance sheet compared with operators that leaned harder on debt during the expansion years. That conservatism tends to translate into steadier wholesale purchasing, more predictable payment terms to suppliers, and less pressure to discount shelf prices to generate short-term cash. In practice, though, the earnings date set for November 2026 will be the next real test of whether margins hold as state markets mature and wholesale pricing continues compressing in several adult-use markets.
- Market capitalization near 2.02 billion dollars places Green Thumb among the larger multi-state cannabis operators by scale.
- Trailing P/E of 15.93 suggests the stock is valued more conservatively than growth-stage cannabis peers.
- Total cash position of 283.59 million dollars provides a buffer against regulatory or tax-related cash flow shocks.
- A "Neutral" consensus rating points to analyst caution rather than conviction in either direction.
None of this changes the underlying reality for consumers or regulators: cannabis remains a tightly controlled product category, subject to state testing requirements, compliant packaging rules, and age-verification mandates at the point of sale. Financial performance at the corporate level doesn't loosen those obligations, and operators watching Green Thumb's results should read them as a market signal, not a shortcut around compliance fundamentals that still govern every transaction at the register.